Market Reports
Method for calculating the VaR (EWMA) based Margin
The method used to derive the VaR Margin requirements for Futues contracts is based on the Initial Margin methodology suggested in the “Varma Committee Report for Risk Containment in Derivatives Market”.
Computation:
-
The standard deviation (Volatility estimate) of prices is computed using the Exponentially Weighted Moving Average method ("EWMA").
-
The Standard Deviation (Volatility estimate) at the end of time period t (σt) is estimated using the Standard Deviation (Volatility estimate) at the end of the previous time period. i.e. as at the end of t-1 time period (σt- 1), and the return (rt) observed during the time period t (price difference in previous two days).
Formula for Standard Deviation (Volatility Estimate) :
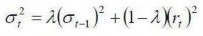
Where,
σ (sigma) means the standard deviation
λ (Lambda) determines how rapidly volatility estimates changes. The value is taken as 0.99 currently.
r (return) is defined as the logarithmic return: rt = ln (St/St-1) where St is the price of the Gold at time t.
Based on the Standard Deviation, the VaR Margin for a particular day is calculated using the below formula.
VaR% = 100 * (EXP(3.5 σ)-1)
Initial Margin = Square Root (MPoR Days) * VaR Margin, where MPoR Days = 3
Notes:
The value of Lambda is taken as 0.99.
-
As per L.C. Gupta committee recommendations, Margins for VaR should be based on 3.5 sigma limits. 3.5 sigma provides more than 99.7% confidence level.
The VaR margin is multiplied by √3 to cover 3 days of Margin Period of Risk (MPOR)
Real Time Computation
The margins shall be computed on real time basis. The computation of portfolio initial margin would have two components. The first is the computation of Initial Margin for each individual contract. At the second stage, these contract Initial Margins would be applied to the actual portfolio positions to compute the portfolio initial margin.
IIBX Clearing shall update EWMA volatility estimates for contracts at discrete time points each day (with a gap of not more than 2 hours between any two consecutive updates and at the end of the trading session) and the latest available scaled up EWMA volatility estimates would be applied to member/client portfolios on a real time basis.
The first Margin file shall be updated before start of market hours, intraday Margin files shall be updated at every two hours interval, and the last Margin file shall be updated at the End of the Day.
Intraday VaR Reports – Futures Market
IIBX publishes Intraday Value at Risk (VaR) reports for Futures Contracts to provide participants with visibility into applicable intraday risk parameters and margin-related information.
The reports support participant monitoring of applicable risk values and facilitate operational readiness during market hours.
Participants may access the latest Intraday VaR files and historical reports through the links below.
| File | Time | Download |
|---|---|---|
| Beginning of the Day | 08:00 | |
| Intraday VaR | 11:00 | |
| Intraday VaR | 13:00 | |
| Intraday VaR | 14:59 |
The reports are published in accordance with applicable operational timelines and Exchange procedures.